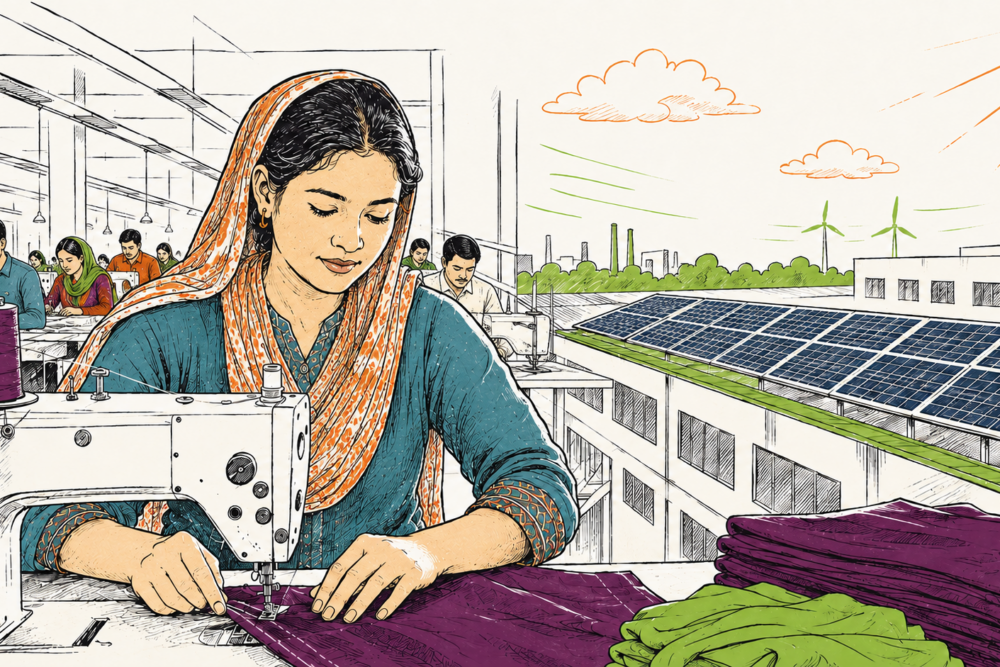
Image concept by Priyong Sabastini
Bangladesh’s ready-made garments (RMG) sector is one of the clearest examples of how globalisation can create economic opportunity while also exposing a country to risks originating far beyond its borders. For decades, Bangladesh’s integration into global supply chains has built an export powerhouse and supported millions of workers, mostly women. But the same global connections that created this success also transmit the effects of climate pressures, geopolitical conflicts and energy-market disruptions directly to factories and workers.
This imbalance is particularly visible in the global climate transition. Bangladesh contributes less than 0.5% of global carbon emissions, yet its RMG sector is expected to cut emissions, comply with increasingly stringent sustainability standards and remain internationally competitive - all at the same time.
This is not an argument against climate action. It is an argument for a just transition in which costs and responsibilities are shared more fairly and the realities of workers and developing countries are properly considered.
Recent global energy crises demonstrate the same unequal distribution of risks. The Russia–Ukraine war and conflicts in the Middle East have disrupted fuel markets, raised import costs, put pressure on Bangladesh’s foreign-currency reserves and increased energy costs for industries. Although Bangladesh has little control over these events, their consequences have travelled through the global economy and reached Bangladesh’s industries.
Since 2022, Bangladesh’s dependence on imported fossil fuels has been steadily but significantly rising, going from 47.7% to 62.5%. This has augmented power generation costs by 83%. The Middle East conflict has furthered this vulnerability, with the government seeking over USD 2 billion in external financing to secure energy imports and manage rising costs. For RMG factories, such instability means higher production costs and greater uncertainty precisely when global buyers and regulators are demanding faster decarbonisation.
Globalisation has therefore placed Bangladesh’s RMG sector under pressure from both directions: evolving EU regulations linked to 2050 net-zero commitments on one side, and rising production costs caused by domestic energy insecurity and international conflicts on the other. Each external shock reinforces the same lesson: a renewable-energy transition is no longer merely a matter of climate compliance. It is essential to the RMG sector’s competitiveness, resilience and business continuity.
These pressures are not only confined to factory balance sheets, but trickle down to factory floors through higher operating costs, production uncertainty, tighter margins and risks to workers’ livelihoods. Workers are often among the first to feel the consequences of such pressures through job insecurity, wage pressure, increased work intensity or weakened workplace protections.
This makes energy insecurity both a business and worker rights issue.
The question is therefore, not whether RMG should pursue a green transition. To forego external reliance, ensure energy security and meet global demands, it must. The more urgent question is how RMG can be supported to meet global climate and trade expectations while safeguarding business and worker rights amid repeated macroeconomic crises.
If energy resilience is a precondition for Bangladesh’s economic and political development, wherein export earnings continue to hinge heavily on the RMG industry, then current policy and budget measures must be assessed against the scale of this need.
The FY2026–27 national budget offers an important opening. The increased focus on renewable energy, particularly, the solar taxation exemption of 0% is a welcome relief for industries seeking to decarbonise, as it significantly brings down upfront solar costs.
However, recent analysis by CPD shows renewable energy accounted for only 1.55% of relevant ADP allocation in FY2021–22, rising to 4.6% in RFY2025–26, while fossil-fuel-based projects continued to receive over 95%. In FY2026–27, it has been found yet again that only 2% of generation-sector allocation is directed to RE, compared with 98% for fossil-fuel-based generation.
This exposes a few major caveats within the budget.
Solar tax relief is necessary, but it is not the same as a just energy transition for RMG. Sector-wide uptake will require clear guidance, technical support, accessible finance and simpler implementation pathways. And, for that, strong energy governance becomes quintessential.
The government does not have to carry the full cost of RMG’s renewable energy transition, but it has an unavoidable and major role in ensuring RMG’s much-needed transition. This is also directly linked to the government’s own development agenda.
For instance, The FY2026-27 budget aims to raise GDP growth to 6.5% and bring down inflation to 7.5% by prioritising investment, production, employment generation and energy security. These targets will be harder to achieve if Bangladesh’s largest export industry is constantly burdened with rising energy costs, energy insecurity, increasing production and operational costs and, global sustainability requirements.
With Bangladesh’s moving average inflation reportedly at 8.63% between June 2025 and May 2026, energy costs cannot be treated as a sectoral concern alone. For the government, investing in the private sector’s energy transition is a practical gateway to stabilise macroeconomic conditions and strengthen energy sovereignty.
But this will require moving beyond isolated incentives towards a coordinated and collaborative transition plan.
First, grid readiness and modernisation must be a top priority, otherwise achieving at least 20% renewable energy in the nation’s total energy share will be a distant reality for 2030, let alone RMG.
Second, export-oriented industries, particularly RMG, need targeted incentives that make decarbonisation a business case for RMG rather than another compliance burden. Factories that invest in renewable energy, improving energy efficiency, meeting safety requirements and tracking emissions could be prioritised for proportionate provisions e.g. tax relief or faster approval support etc. This would encourage more factories to invest early, while helping secure Bangladesh RMG’s global competitive edge. These incentives must also be accessible for all factories, including SMEs.
Third, collaborative approaches to strategically achieve an energy transition must be identified, with the government playing the core convening role. Industry associations, brands, manufacturers, financial institutions, renewable energy service providers and worker representatives need to be brought into the same transition conversation.
Cluster-based renewable energy solutions for RMG and other export-oriented industries could potentially be explored. Factories located in industrial zones or production clusters could be supported through shared renewable energy, safety, compliance and financing frameworks. This would allow smaller factories to attain the necessary cushioning to parallelly transition alongside larger counterparts. Public-private partnership should also be strengthened to unlock investment at scale.
Fourth, industrial decarbonisation must be backed by stronger research, data and actionable measures.
Finally, the transition must equally invest in people. Workers should not be treated only as passive recipients of adverse climate change or industrial crisis impacts. Worker can and should also be active change agents in the overall energy transition and climate action discourse.
Government must invest in renewable energy skills, strengthen worker awareness, enable social dialogue, and ensure meaningful stakeholder engagement with workers at the forefront of the discussion. Energy resilience is not separate from worker wellbeing. Wage reforms and labour protections matter, but their implications will not be effective if the economy repeatedly absorbs energy crises costs.
A greener RMG sector will only be truly resilient if energy security, business viability and worker wellbeing are treated as part of the same transition.
Bangladesh has already learned the cost of energy dependence. Before the next shock arrives, RMG’s energy transition must be planned, financed and governed in a way that strengthens competitiveness, protects workers and makes renewable energy a real opportunity rather than another uneven burden.
- Munir Uddin Shamim, Director of Programme, Evidence & Learning
And Priyong Sabastini, Senior Programme Officer


